The global display technologies market is set for sustained expansion as demand for smarter devices, high resolution screens, automotive displays and digital signage pushes the industry towards a projected $267.52 billion valuation by 2033.
According to a market outlook, the sector is expected to rise from approximately $150 billion in 2024 to $267.52 billion by 2033, representing a compound annual growth rate of 7.5 percent between 2026 and 2033.
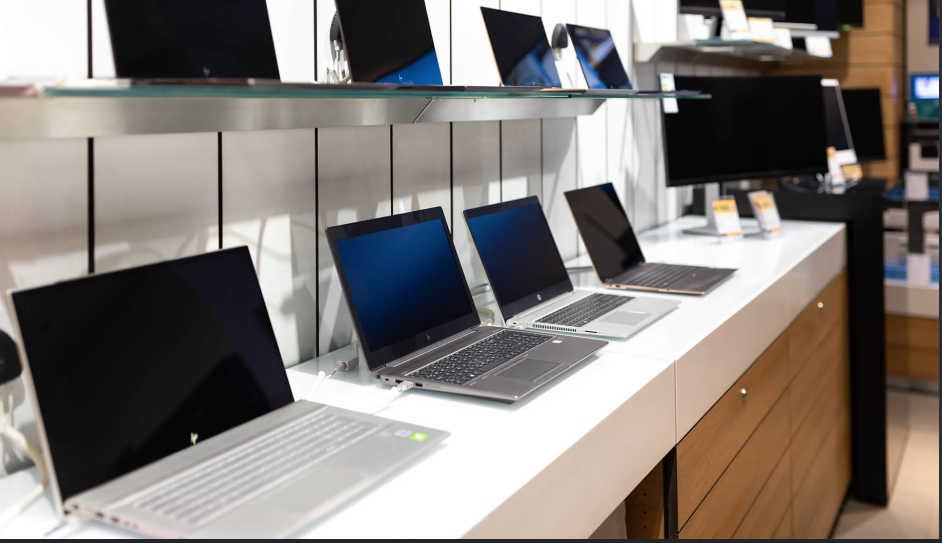
The projected growth reflects a major shift in how consumers and businesses interact with digital content. Smartphones, televisions, laptops and tablets continue to generate substantial demand, while automotive manufacturers, retailers and industrial operators are increasingly incorporating sophisticated display systems into their products and operations.
At the heart of the market expansion is the rapid development of display technologies such as OLED, microLED, QLED and flexible displays. These technologies are enabling thinner, brighter and more energy efficient screens while also opening new possibilities for foldable, transparent and interactive displays.
The transition from conventional LCD technology towards more advanced display architectures is also reshaping competition across the industry. Manufacturers are investing heavily in research, production capacity and intellectual property as customers demand sharper images, improved colour reproduction, faster refresh rates and increasingly flexible form factors.
Consumer electronics remains the largest source of demand, particularly as manufacturers introduce foldable smartphones, larger screens and increasingly sophisticated viewing experiences. The growing appetite for high quality visual content continues to support investment across the display supply chain.
The automotive sector, however, is emerging as another major growth engine. Automakers are incorporating larger digital cockpits, advanced infotainment screens and augmented reality head up displays into vehicles, particularly as electric and increasingly automated vehicles become more common.
This shift is changing the requirements placed on display manufacturers. Automotive customers increasingly demand screens that combine high resolution with durability, low energy consumption and reliable performance.
Digital signage is providing another avenue for expansion. Retail businesses, public institutions and smart city projects are adopting large format, high brightness and interactive displays to deliver advertising, information and public services.
Industrial applications are also expanding as manufacturers and logistics companies deploy rugged, high resolution displays to support monitoring, automation and operational decision making.
Geographically, Asia Pacific remains a major force in the display industry, supported by its large consumer electronics market and concentration of manufacturing capacity.
South Korea, China and Taiwan remain particularly important production centres, while North America and Europe continue to generate significant demand for advanced display solutions.
The supply chain, however, remains capital intensive. Major manufacturers must commit substantial resources to fabrication plants, equipment upgrades, research and development and specialised materials. New production facilities can also require long lead times, making capacity planning critical as demand shifts between technologies.
Samsung, LG Display and BOE remain among the major companies shaping global production and technological development, alongside players such as Innolux, AU Optronics, Panasonic and Universal Display.
The competitive environment is also attracting specialised companies working on emerging applications, including microLED, augmented reality, virtual reality and other next generation display formats.
Beyond the established market, flexible and transparent displays could create new application categories across consumer electronics, automotive, healthcare, education and wearable technology.
At the same time, advances in augmented and virtual reality are increasing demand for displays with high pixel density, rapid refresh rates and low latency.
Environmental considerations are also influencing the direction of the industry. Manufacturers face increasing pressure to improve energy efficiency, reduce environmental impact and develop more responsible approaches to electronic waste and material use.
For investors and technology companies, these developments are creating opportunities across advanced manufacturing, display materials, flexible screens, microLED and related technologies. Strategic partnerships and investment in production capacity are expected to remain important as companies compete to capture emerging demand.
The market outlook therefore points to a display industry moving beyond conventional screens into a broader ecosystem of connected, flexible and intelligent visual technologies.
With consumer electronics providing scale and automotive, digital signage, industrial and emerging applications opening new revenue streams, the global display technologies market is projected to maintain its growth trajectory through 2033.



Comment
No comments found.